In March, Omar, a freelance web designer, signed seven new clients. It was his best month for new business ever. He told his friends he was finally "making it."
By June, he was exhausted. Three of the seven clients sent changes at midnight, argued about invoices and kept adding "one small thing" to every project. Two paid late. One left a bad review. His income barely moved, and he'd never worked so many hours.
Omar had fallen for one of the most common traps in business: believing that more clients automatically means more success. It doesn't. What matters is who those clients are, and what they cost you.
- A difficult client costs more than their invoice suggests: extra hours, stress and lost focus.
- In many businesses, a small group of clients produces most of the profit, and a different small group causes most of the headaches.
- Score your clients on payment, respect, fit and effort, then spend more time on the best ones.
- Red flags usually appear before the contract is signed, so listen carefully in the first conversation.
- Fewer, better clients give you more referrals, fairer prices and the energy to do great work.
The Busiest Month That Made No Money
When you start a business, every client feels like a victory. You say yes to everything because you're afraid the next one won't come. That's understandable. But somewhere along the way, the strategy needs to change from "how do I get more?" to "who do I want to serve?"
An unhappy client is rarely quiet. They take up your time, drain your team's morale and, when they finally leave, they can tell many other people about it. A happy client does the opposite. They pay on time, trust your judgment, return and recommend you to people just like them.
Ten angry clients don't give you ten times the income. They give you ten times the stress.
The Hidden Math of a Difficult Client
Look at two real-world-style examples. Both clients hire a designer for a website.
Client B pays $1,500, gives clear feedback in one round and needs 8 hours. Real rate: $187 an hour.
Client B is paying you almost twice as much for your time, and you also get 12 hours back to find or serve another good client.
That doesn't even include the invisible costs: the stress that follows you home, the creative energy you lose and the great client you didn't have time to take on because you were busy with the difficult one.
The 80/20 Pattern
More than a century ago, the Italian economist Vilfredo Pareto noticed that roughly 80% of the land in Italy was owned by about 20% of the people. The idea was later generalized into the Pareto principle, often called the 80/20 rule: a small share of causes produces a large share of results.
It's not a law of nature, and the numbers are rarely exactly 80 and 20. But in business, the pattern shows up often. A small group of customers tends to bring most of your revenue and most of your referrals. And another small group often takes up a surprising amount of your time and energy.
Here's an exercise: list your last ten clients. Next to each one, write how much they paid you, and how many hours they really took. You may be surprised which names are at the top and bottom of the list.
Score Your Clients
Instead of going on gut feeling, give each client a quick score. Rate each of these from 1 (poor) to 5 (excellent):
1. Payment
Do they pay the agreed amount, on time, without chasing?
2. Respect
Do they treat you and your team as experts and as people?
3. Fit
Is this the kind of work you do best and want more of?
4. Effort
Is the time they need in proportion to what they pay?
5. Growth
Do they refer others, come back or give you chances to do great work?
Add up the scores. Clients with 20 or more are your core, so protect them and give them your best attention. Clients below 12 deserve a conversation: can the relationship be fixed with clearer boundaries, a higher price or a new process? If not, it may be time to let them go.
Red Flags to Spot Early
Most difficult clients show their colors before you sign. Listen for these in the first call or email:
- They rush you to start without a clear brief. Unclear goals become endless revisions.
- They push hard on price. People who value only the cheapest option rarely value your work later.
- They speak badly about every past supplier. You may be next on the list.
- They won't sign or pay a deposit. Commitment at the start predicts commitment later.
- They ignore your process. If they don't respect your timeline now, they won't later.
One red flag doesn't mean you should refuse. But two or three together are a signal. If you want to learn how to say no kindly and professionally, read our guide on the art of saying no.
How to Shift Toward Better Clients
Raise your prices
Higher prices naturally filter out clients who don't value your work. If the idea scares you, our guide to premium pricing shows how.
Write down your ideal client
Describe the clients you most enjoy working with: their industry, size, values and the problem they have. Use this in your marketing so you attract more of them.
Create a clear process
A written scope, a set number of revisions and clear payment terms protect both sides. Good clients appreciate clarity.
Ask your best clients for introductions
Great clients tend to know people like themselves. A simple "do you know anyone who'd benefit from this?" works well.
Exit gracefully
When a client isn't a fit, finish current work, suggest someone else and part on good terms. No drama, no blame.
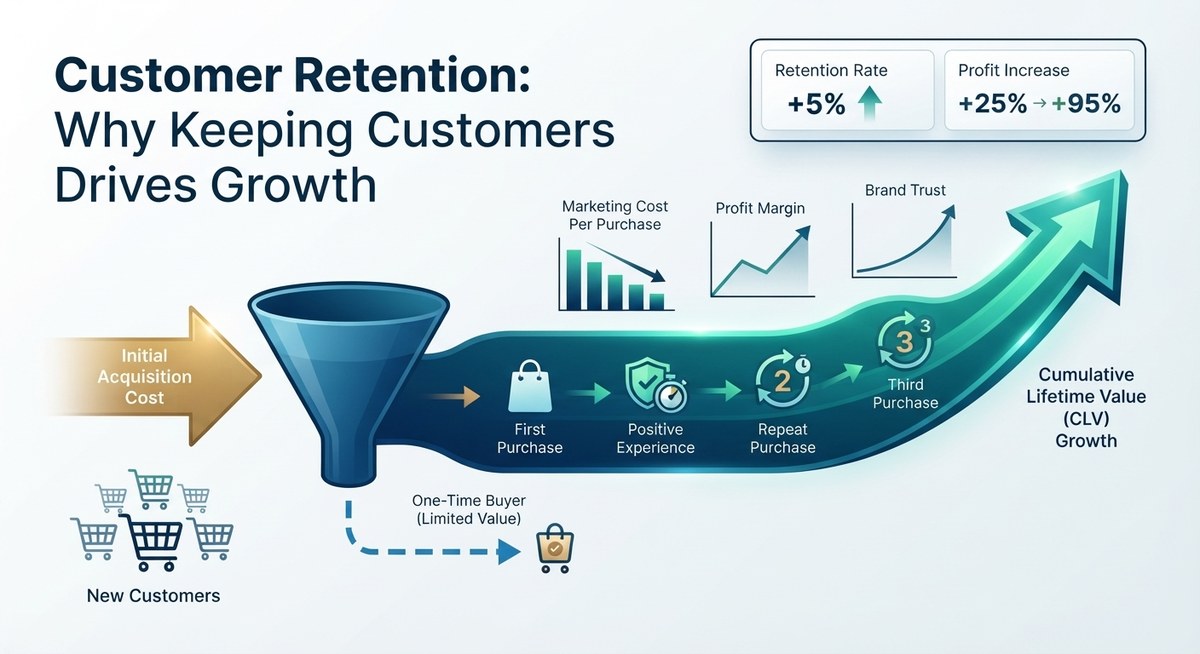
Keeping your best clients happy matters just as much as choosing them. Our article on customer retention explains why long-term clients are the foundation of a healthy business.
Conclusion: Build a Business You Enjoy Running
Omar did something hard in July. He politely ended work with two of his most difficult clients, raised his prices by 20% and created a one-page process for new projects. The next quarter, he had fewer clients, higher income and, for the first time in a year, free weekends.
This week, list your last ten clients, score them and identify your top three and bottom three. Then give your best energy to the clients who deserve it. One happy client is worth more than ten angry ones.
Frequently Asked Questions
Is it better to have fewer clients?
Often, yes. A smaller group of clients who pay well, respect your time and refer others can bring more profit and less stress than a large group of difficult ones.
What is the 80/20 rule in business?
The Pareto principle suggests that a small share of causes produces a large share of results. In business, a small group of customers often brings most of your revenue and referrals.
How do I know if a client is a bad fit?
Look for late payments, constant scope changes, disrespect, pressure on price and poor communication. Scoring clients on payment, respect, fit, effort and growth makes it clearer.
How do I end a client relationship politely?
Finish current commitments, explain that you're focusing your services in a different direction, recommend an alternative if possible and keep the tone calm and professional.
Will raising my prices lose clients?
It may lose some price-sensitive clients, but it often attracts clients who value your work and leaves you more time and energy for them.